Product administration
Whole life insurance policy administration
Whole life insurance covers the life assured for their entire life rather than for a fixed term, and pays the sum assured whenever death occurs as long as premiums have been kept up. Because part of each premium builds a reserve, a whole life policy acquires a surrender value that the policyholder can take in cash, a paid-up value if they stop paying, and often the ability to borrow against the policy.
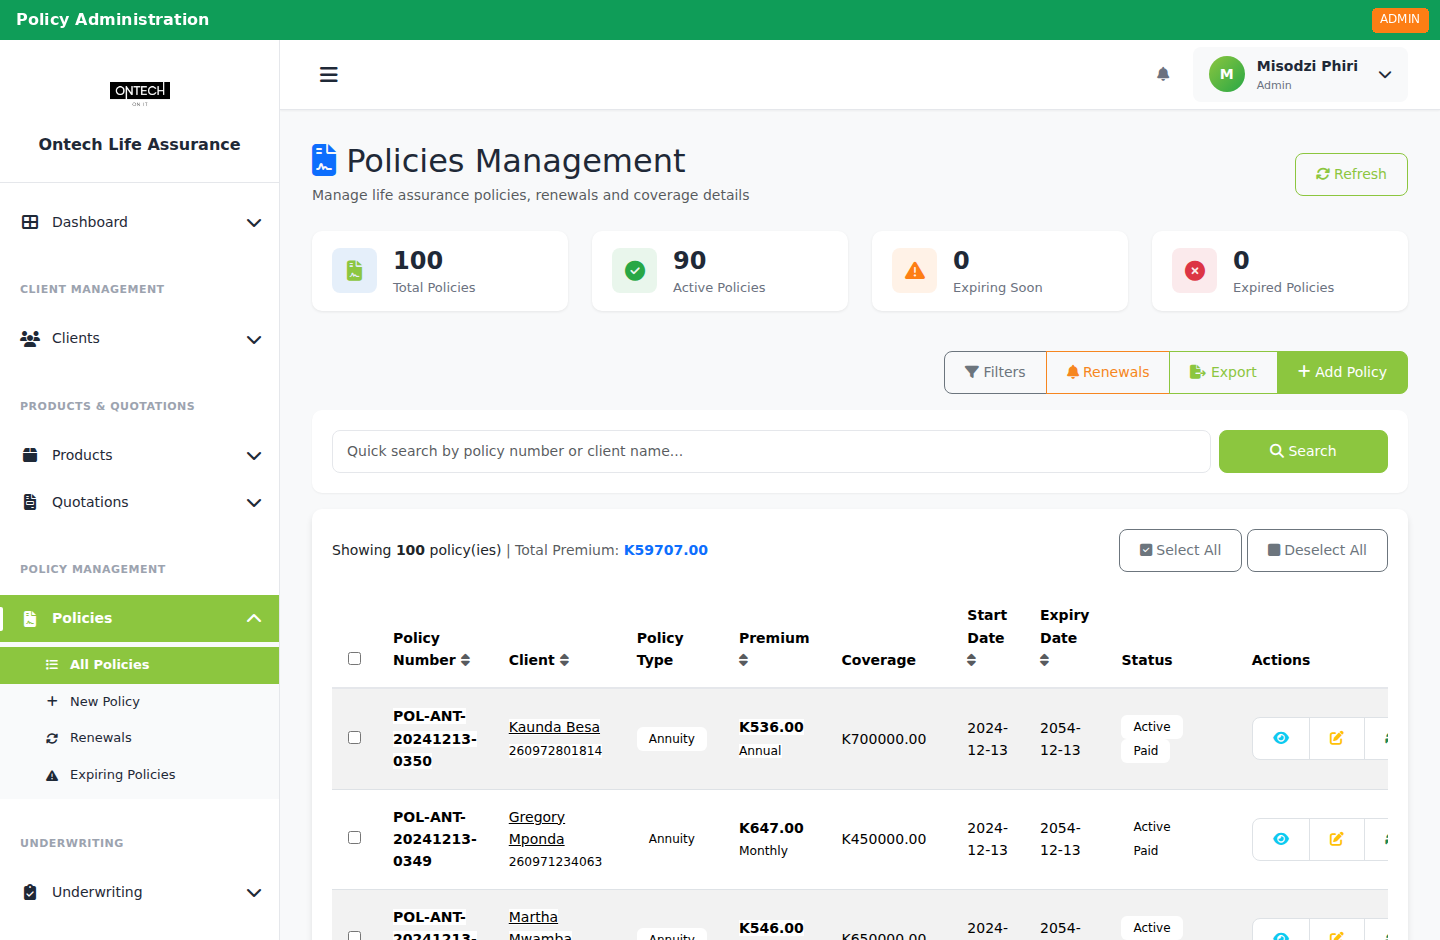
Whole life administration therefore has to do more than bill premiums: it must calculate and track surrender and paid-up values, manage policy loans and their interest, allocate bonuses where the product participates in profits, and handle a claim that may arrive decades after issue. Ontech LifeI ERP administers these events for life insurers in Zambia from one policy record.
Key capabilities
Surrender value calculation
Compute the cash value payable on surrender from the product's surrender basis, show it to staff and policyholders, and process full or partial surrenders.
Paid-up values
When a policyholder stops paying after the qualifying period, convert the policy to a reduced paid-up sum assured instead of lapsing it.
Policy loans
Grant loans against the surrender value, accrue interest, record repayments through Mobile Money, and deduct outstanding balances from any benefit.
Bonus and surplus allocation
Declare reversionary or terminal bonuses on participating policies and add them to the sum assured on the policy record.
Long-duration premium management
Bill and collect premiums for decades, handle frequency changes and premium holidays, and keep an unbroken payment history.
Beneficiary and endorsement management
Record beneficiary changes, assignments and other endorsements with effective dates and an audit trail.
Death and maturity claims
Settle the sum assured plus bonuses less any policy loan when the claim is admitted.
How it works
- The whole life product is configured with its premium rates, surrender basis, paid-up rules, loan terms and bonus participation.
- The policy is quoted, underwritten and issued, and premiums are collected on the agreed frequency.
- Each year the system updates the policy's reserve-based values so surrender and paid-up amounts are always current.
- Policyholders can request a surrender quote, a policy loan or a change of beneficiary through the portal, app or an agent.
- Declared bonuses are posted to participating policies and reflected in the sum assured.
- On death, the claim is registered and settled for the sum assured plus bonuses, less any loan balance.
Benefits
Accurate values on demand
Staff and policyholders see the current surrender and paid-up value without a manual actuarial calculation.
Retention instead of lapse
Paid-up conversion, premium holidays and policy loans give policyholders alternatives to losing cover when money is tight.
Correct claim amounts
Bonuses, loans and arrears are all on the policy, so the claim payable is calculated from the record rather than reconstructed.
Long-term data integrity
A whole life policy can outlive several administration systems; a single audited record protects the insurer and the policyholder over decades.
Who it is for
- Life insurers in Zambia with an in-force book of whole life or funeral-type whole life policies.
- Insurers offering participating (with-profits) whole life products that declare bonuses.
- Companies migrating whole life policies from spreadsheets or legacy systems that cannot calculate surrender values.
Zambia-specific considerations
Whole life cover in Zambia is commonly sold as family or funeral protection with modest monthly premiums, so the ability to take a premium holiday, convert to paid-up, or borrow against the policy is important to keeping policies in force through periods of financial pressure.
Surrender values, paid-up values and policy loans affect the reserves and liabilities a long-term insurer reports to the Pensions and Insurance Authority and under IFRS 17. Administering them in the same system as the ledger keeps the operational and financial views consistent.
How Ontech LifeI ERP addresses this
Dedicated surrender and policy loan modules
Ontech LifeI ERP has specific modules for surrender values and policy loans rather than treating them as manual adjustments, so quotes, approvals and postings follow a defined workflow.
Bonus and surplus management
The life financial module records bonus declarations and applies them to participating policies, with the actuarial module supporting the reserve calculations behind them.
Loan repayments through Mobile Money
Policy loan instalments can be repaid through MTN Mobile Money, Airtel Money or Zamtel Kwacha and are matched to the loan account automatically.
Frequently asked questions
What is whole life insurance?
Whole life insurance covers the life assured for their entire lifetime and pays the sum assured on death whenever it occurs, provided premiums are maintained. Part of the premium builds a cash value, so the policy can be surrendered, made paid-up or borrowed against.
What is a surrender value?
The surrender value is the cash amount an insurer pays if the policyholder cancels a whole life or endowment policy before a claim. It is based on the reserve built up under the policy and the product's surrender basis, and is usually low in the early years.
What is a paid-up value?
If premiums stop after a qualifying period, the policy can continue with a reduced sum assured and no further premiums. That reduced sum assured is the paid-up value.
How do policy loans work?
A policy loan lets the policyholder borrow up to a percentage of the surrender value from the insurer. Interest accrues, and any outstanding balance is deducted from the surrender value or claim payment. Ontech LifeI ERP tracks the loan, interest and repayments on the policy.
Does Ontech LifeI ERP handle bonuses on with-profits policies?
Yes. Declared bonuses are recorded in the life financial module and applied to participating policies, increasing the sum assured shown on the policy and used in claims.
See Ontech LifeI ERP for your company
Book a demo with Ontech Solutions in Lusaka and see policy administration, claims, Mobile Money collection and PIA reporting working together in one platform.
Last updated 2026-09-13. Published by Ontech Solutions, Lusaka, Zambia.