Product administration
Annuity and pension payout administration
An annuity is a contract in which a life insurer pays a regular income, usually for the rest of the annuitant's life, in exchange for a lump sum or a series of premiums. An immediate annuity starts paying straight away; a deferred annuity accumulates first and starts paying at a chosen retirement date. Annuities are how many pension savings are turned into a guaranteed income.
Annuity administration is about paying the right amount to the right person on time for as long as they live: setting up the payment schedule, applying escalation, verifying the annuitant is still alive, handling joint-life and guaranteed periods, and paying any balance to beneficiaries. Ontech LifeI ERP administers annuities and pension payouts for life insurers in Zambia.
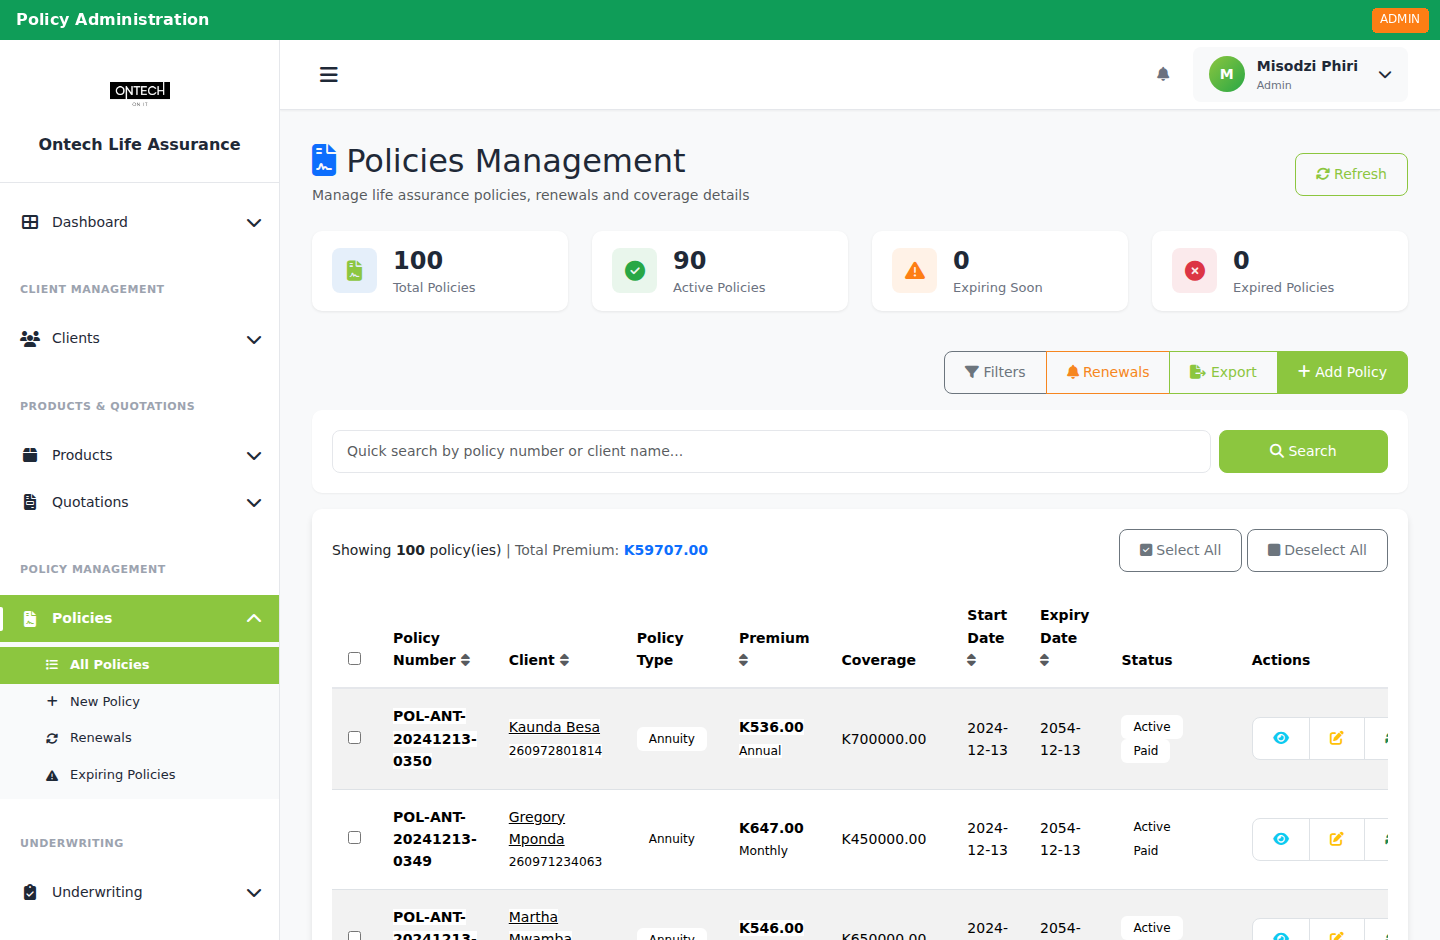
Key capabilities
Annuity quotation and setup
Quote immediate and deferred annuities from the purchase price, age, gender, escalation and guarantee options, and set up the payment schedule on issue.
Regular payment runs
Generate monthly or other periodic annuity payments, pay through bank or Mobile Money, and post each run to the ledger with maker-checker approval.
Escalation and options
Apply fixed or indexed increases, joint-life continuation to a spouse, and guaranteed payment periods as configured on the product.
Proof of life
Schedule and record life certificates, suspend payments when proof is overdue, and resume with arrears when it arrives.
Deferred accumulation
Collect contributions during the deferment period, track the accumulated fund, and convert it to income at the vesting date.
Death and guarantee handling
On the annuitant's death, stop payments, pay any remaining guaranteed instalments or spouse's pension, and close the contract.
How it works
- The annuity product is configured with its rates, escalation options, guarantee periods and joint-life rules.
- A quotation is produced from the purchase price or the accumulated deferred fund, and the annuity is issued.
- The payment schedule is created and the first payment run is approved and paid.
- Each period the system generates the payment run, applies any escalation, and pays annuitants whose proof of life is current.
- Life certificates are requested on schedule; overdue cases are suspended until proof is received.
- On death, remaining guaranteed payments or a spouse's pension are paid and the annuity is closed.
Benefits
Reliable income for annuitants
Scheduled runs and approved payment files mean pensioners are paid on the same day each period.
Reduced overpayment risk
Proof-of-life tracking stops payments continuing after a death goes unreported.
Correct treatment of options
Escalation, guarantees and joint-life terms are applied by the system from the product rules rather than remembered by staff.
Clean liabilities
Annuity payments and the remaining liability flow to the ledger and actuarial modules from the same records.
Who it is for
- Life insurers in Zambia writing annuities or paying pensions from retirement savings.
- Insurers administering pension funds or group retirement schemes that need a payout engine.
- Companies replacing manual annuity payment schedules with an audited payment run.
Zambia-specific considerations
In Zambia, retirement income is provided through the National Pension Scheme Authority (NAPSA), occupational pension schemes and individual products from long-term insurers. Life insurers and pension funds that pay annuities are regulated by the Pensions and Insurance Authority, which oversees both insurance and pensions.
Many annuitants prefer to receive income through Mobile Money rather than a bank account, and proof of life is easier to collect through a mobile channel than by requiring branch visits. An annuity system built for Zambia should support both.
How Ontech LifeI ERP addresses this
Annuity and pension modules together
Ontech LifeI ERP includes both an annuity product line and a pension fund management module, so accumulation and payout can be run in one system.
Payment runs with controls
Annuity payment runs pass through maker-checker approval before release, and every run is posted to the general ledger.
Mobile Money payouts and mobile proof of life
Annuities can be paid to MTN Mobile Money, Airtel Money or Zamtel Kwacha accounts, and annuitants can be contacted by SMS or WhatsApp for life certificates.
Frequently asked questions
What is an annuity?
An annuity is a contract under which an insurer pays a regular income, typically for life, in return for a lump sum or accumulated savings. It converts a pension pot into guaranteed income.
What is the difference between an immediate and a deferred annuity?
An immediate annuity starts paying income shortly after the purchase price is paid. A deferred annuity accumulates contributions first and begins paying at a future date, usually retirement.
What is a guaranteed period on an annuity?
A guaranteed period means payments continue for a minimum number of years even if the annuitant dies earlier, with the balance paid to beneficiaries. Ontech LifeI ERP applies this from the product configuration.
How does proof of life work?
The insurer periodically asks the annuitant to confirm they are alive, usually with a life certificate. Ontech LifeI ERP schedules these requests, suspends payments when proof is overdue and resumes them with arrears once it is received.
Can annuities be paid through Mobile Money in Zambia?
Yes. Ontech LifeI ERP can pay annuity instalments to MTN Mobile Money, Airtel Money or Zamtel Kwacha accounts as well as to bank accounts.
Sources
See Ontech LifeI ERP for your company
Book a demo with Ontech Solutions in Lusaka and see policy administration, claims, Mobile Money collection and PIA reporting working together in one platform.
Last updated 2026-09-13. Published by Ontech Solutions, Lusaka, Zambia.